For auctions and fixed-date sales, the new requirements apply to sales held on and from 16 October 2026. The changes are designed to increase property-price transparency and give prospective buyers better access to meaningful information before and after a residential property sale. Readers can independently confirm the commencement dates and principal reforms through Consumer Affairs Victoria’s summary of the new property sales laws.
For Victorian estate agents and agents’ representatives, understanding the new Property Price Statement Guidelines is important because the reforms affect property advertising, comparable sales, reserve-price procedures, written offers, sold-price publication and agency recordkeeping. This guide explains the principal changes and highlights practical procedures that real estate agencies should review.
What is a Property Price Statement?
The Property Price Statement, commonly referred to as the PPS, replaces the former Statement of Information. Agents must prepare the approved Property Price Statement for residential properties they are engaged to sell, including applicable properties that are not publicly advertised.
The PPS continues to provide important price information but now carries additional disclosure requirements. These include key features of the property being sold and of the comparable properties relied upon, together with updating requirements at different stages of a sales campaign. The current official Property Price Statement requirements are published by Consumer Affairs Victoria.
For auctions and fixed-date sales held on or after 16 October 2026, the new PPS requirements operate alongside the new reserve-price rules. For other applicable residential sales, the new Property Price Statement requirements commenced on 1 October 2026.
What are the major New Property Price Statement Laws?
The reforms involve considerably more than replacing the words “Statement of Information” with “Property Price Statement”. They introduce new obligations affecting how agents prepare pricing information, advertise residential property, select comparable sales, obtain reserve prices and disclose final sale results.
- The Statement of Information has been replaced by the Property Price Statement.
- Key features of the property being sold must be included.
- Key features of comparable properties must also be provided.
- Agents must use one or two qualifying comparable properties where three cannot be identified.
- The PPS must be displayed more prominently in online advertising.
- Reserve prices must be published at least seven days before applicable auctions and fixed-date sales.
- Advertising must be updated when the reserve price is received.
- Applicable final sold prices must be published after the sale becomes unconditional.
- The updated PPS must remain publicly available online for at least 18 months after an unconditional sale.
These changes affect several stages of a residential sales campaign rather than creating one isolated compliance task. Agencies therefore need to think of the PPS as an active document that may require monitoring and updating throughout the listing, sale and post-sale process. The principal changes and commencement dates can be checked against CAV’s reform timetable.
Property Price Statement Guidelines: what information must be included?
The Property Price Statement must contain the applicable indicative selling price and comparable-property information, together with other prescribed information. The indicative selling price may be expressed as a single figure or a range of no more than 10%, and it must comply with Victoria’s existing underquoting requirements.
The new rules also require agents to provide important characteristics of both the property being sold and the comparable properties relied upon. Under the CAV Property Price Statement guidelines, these key features include:
- type of building
- number of bedrooms
- number of bathrooms
- number of car spaces
- internal built area or floor space in square metres
- total land size in square metres.
These additional details give prospective buyers more context when considering the sales evidence used to support an estimated selling price. Two properties may have similar sale prices but differ materially in size, accommodation, land area or condition, so providing additional property characteristics can help make the comparison more meaningful.
New rules for comparable properties
Comparable properties remain an important part of estimating and explaining a residential property’s selling price. For a property within metropolitan Melbourne, a comparable property generally needs to be of a similar standard or condition, have sold within the previous six months and be located within two kilometres of the property for sale. Outside metropolitan Melbourne, the applicable period is generally 18 months and the distance is five kilometres.
Agents selecting comparable sales should also consider matters such as the condition of the properties, location, sale date, age, renovation status, neighbourhood features and other relevant differences. The regulator sets these criteria out in its comparable-property guidance.
Where three qualifying comparable properties exist, the agent must take into account the three most comparable properties. Where three cannot be identified but one or two qualifying comparable properties can be found, those one or two properties must now be taken into account rather than being disregarded merely because there are fewer than three.
The Property Price Statement must provide relevant information about the comparable properties, including the address, sale date, sale price and key characteristics. Agencies should also maintain records supporting how comparable properties were selected and how the available sales evidence informed the estimated selling price.
Property Price Statements must be prominent in online advertising
One of the most visible changes concerns where prospective buyers can find the PPS in online property advertisements. The Property Price Statement, or a direct link to it, must be displayed prominently rather than being difficult to locate near the bottom of a listing.
For online advertisements, the PPS must be displayed or linked within the first visible part of the main advertisement and immediately next to the advertised property price. Physical advertising containing specific property information must also include an internet address or QR code that links to the Property Price Statement.
This creates an important practical consideration for agencies using multiple systems. The presentation of PPS information should be reviewed across the agency website, property portals, CRM-generated listings, automated feeds, brochures, signboards and other marketing materials rather than assuming the requirements are satisfied simply because a PPS has been created.
Reserve prices must be disclosed seven days before auctions and fixed-date sales
One of the most significant elements of the New Property Price Statement Laws is mandatory advance disclosure of the seller’s reserve price for applicable residential auctions and fixed-date sales. The estate agent must request the reserve price in writing and the confirmed reserve must be published at least seven days before the scheduled sale.
When requesting the reserve price, the agent must provide the seller with advice regarding a recommended reserve price and the reasons supporting that recommendation. The seller may accept the recommendation, request another recommendation or nominate another reserve price, with the confirmed reserve communicated in writing.
The published reserve must be expressed as a single dollar amount. Qualifying terminology or symbols such as “from”, “over”, “starting at” or “+” cannot be used. These requirements are set out in CAV’s reserve-price disclosure requirements.
What happens if the reserve price is not disclosed in time?
If the reserve price has not been published for the required seven-day period, the scheduled auction or fixed-date sale cannot proceed. For example, an auction or fixed-date sale held on 16 October 2026 required the reserve price to have been disclosed by 9 October 2026. Readers can verify that example directly in Consumer Affairs Victoria’s commencement guidance.
This requirement creates an important operational deadline for agencies. Procedures should cover requesting the reserve, obtaining written confirmation, recording when it was received, updating the PPS and advertising, and confirming that the full disclosure period has elapsed before the scheduled sale occurs.
What happens if the seller changes the reserve price?
A seller can change a reserve price that has already been published, but doing so affects the timing of the sale. If the publicly disclosed reserve changes, the revised figure must generally remain publicly available for another full seven days before the auction or fixed-date sale can proceed.
The requirement applies whether the seller increases or decreases the reserve. Agents should therefore make sellers aware of the timing consequences before changing an already published reserve close to a scheduled sale, and should check the current CAV industry Q&A where unusual circumstances arise.
Advertising must be updated when the reserve price is received
Once an agent receives the seller’s reserve price, advertising and marketing materials must be reviewed and updated in accordance with the new requirements. This includes the Property Price Statement and relevant online and physical advertising used during the campaign.
Consumer Affairs Victoria states that online advertising must be updated within one business day after the agent receives the seller’s reserve price. Agencies publishing through multiple property portals and automated marketing systems therefore need clear internal responsibility for making and checking those changes.
Existing underquoting obligations also continue to apply. Property advertising must not be below the applicable estimated selling price, the seller’s asking price or a written offer that has already been rejected because the seller considered the price too low.
What happens when a written offer is rejected?
A written offer does not necessarily have to appear in a formal contract of sale before it becomes relevant to the underquoting rules. An offer in another written form may qualify where it identifies the price being offered and the other proposed terms.
If the seller rejects a written offer because the price is considered too low, the indicative selling price and applicable advertising may need to be updated. If the offer was rejected for another reason, such as unacceptable conditions or settlement terms, the same price-update requirement does not automatically arise. Agents should refer to the current Victorian underquoting rules for written offers when assessing a rejected offer.
Sold prices must now be published
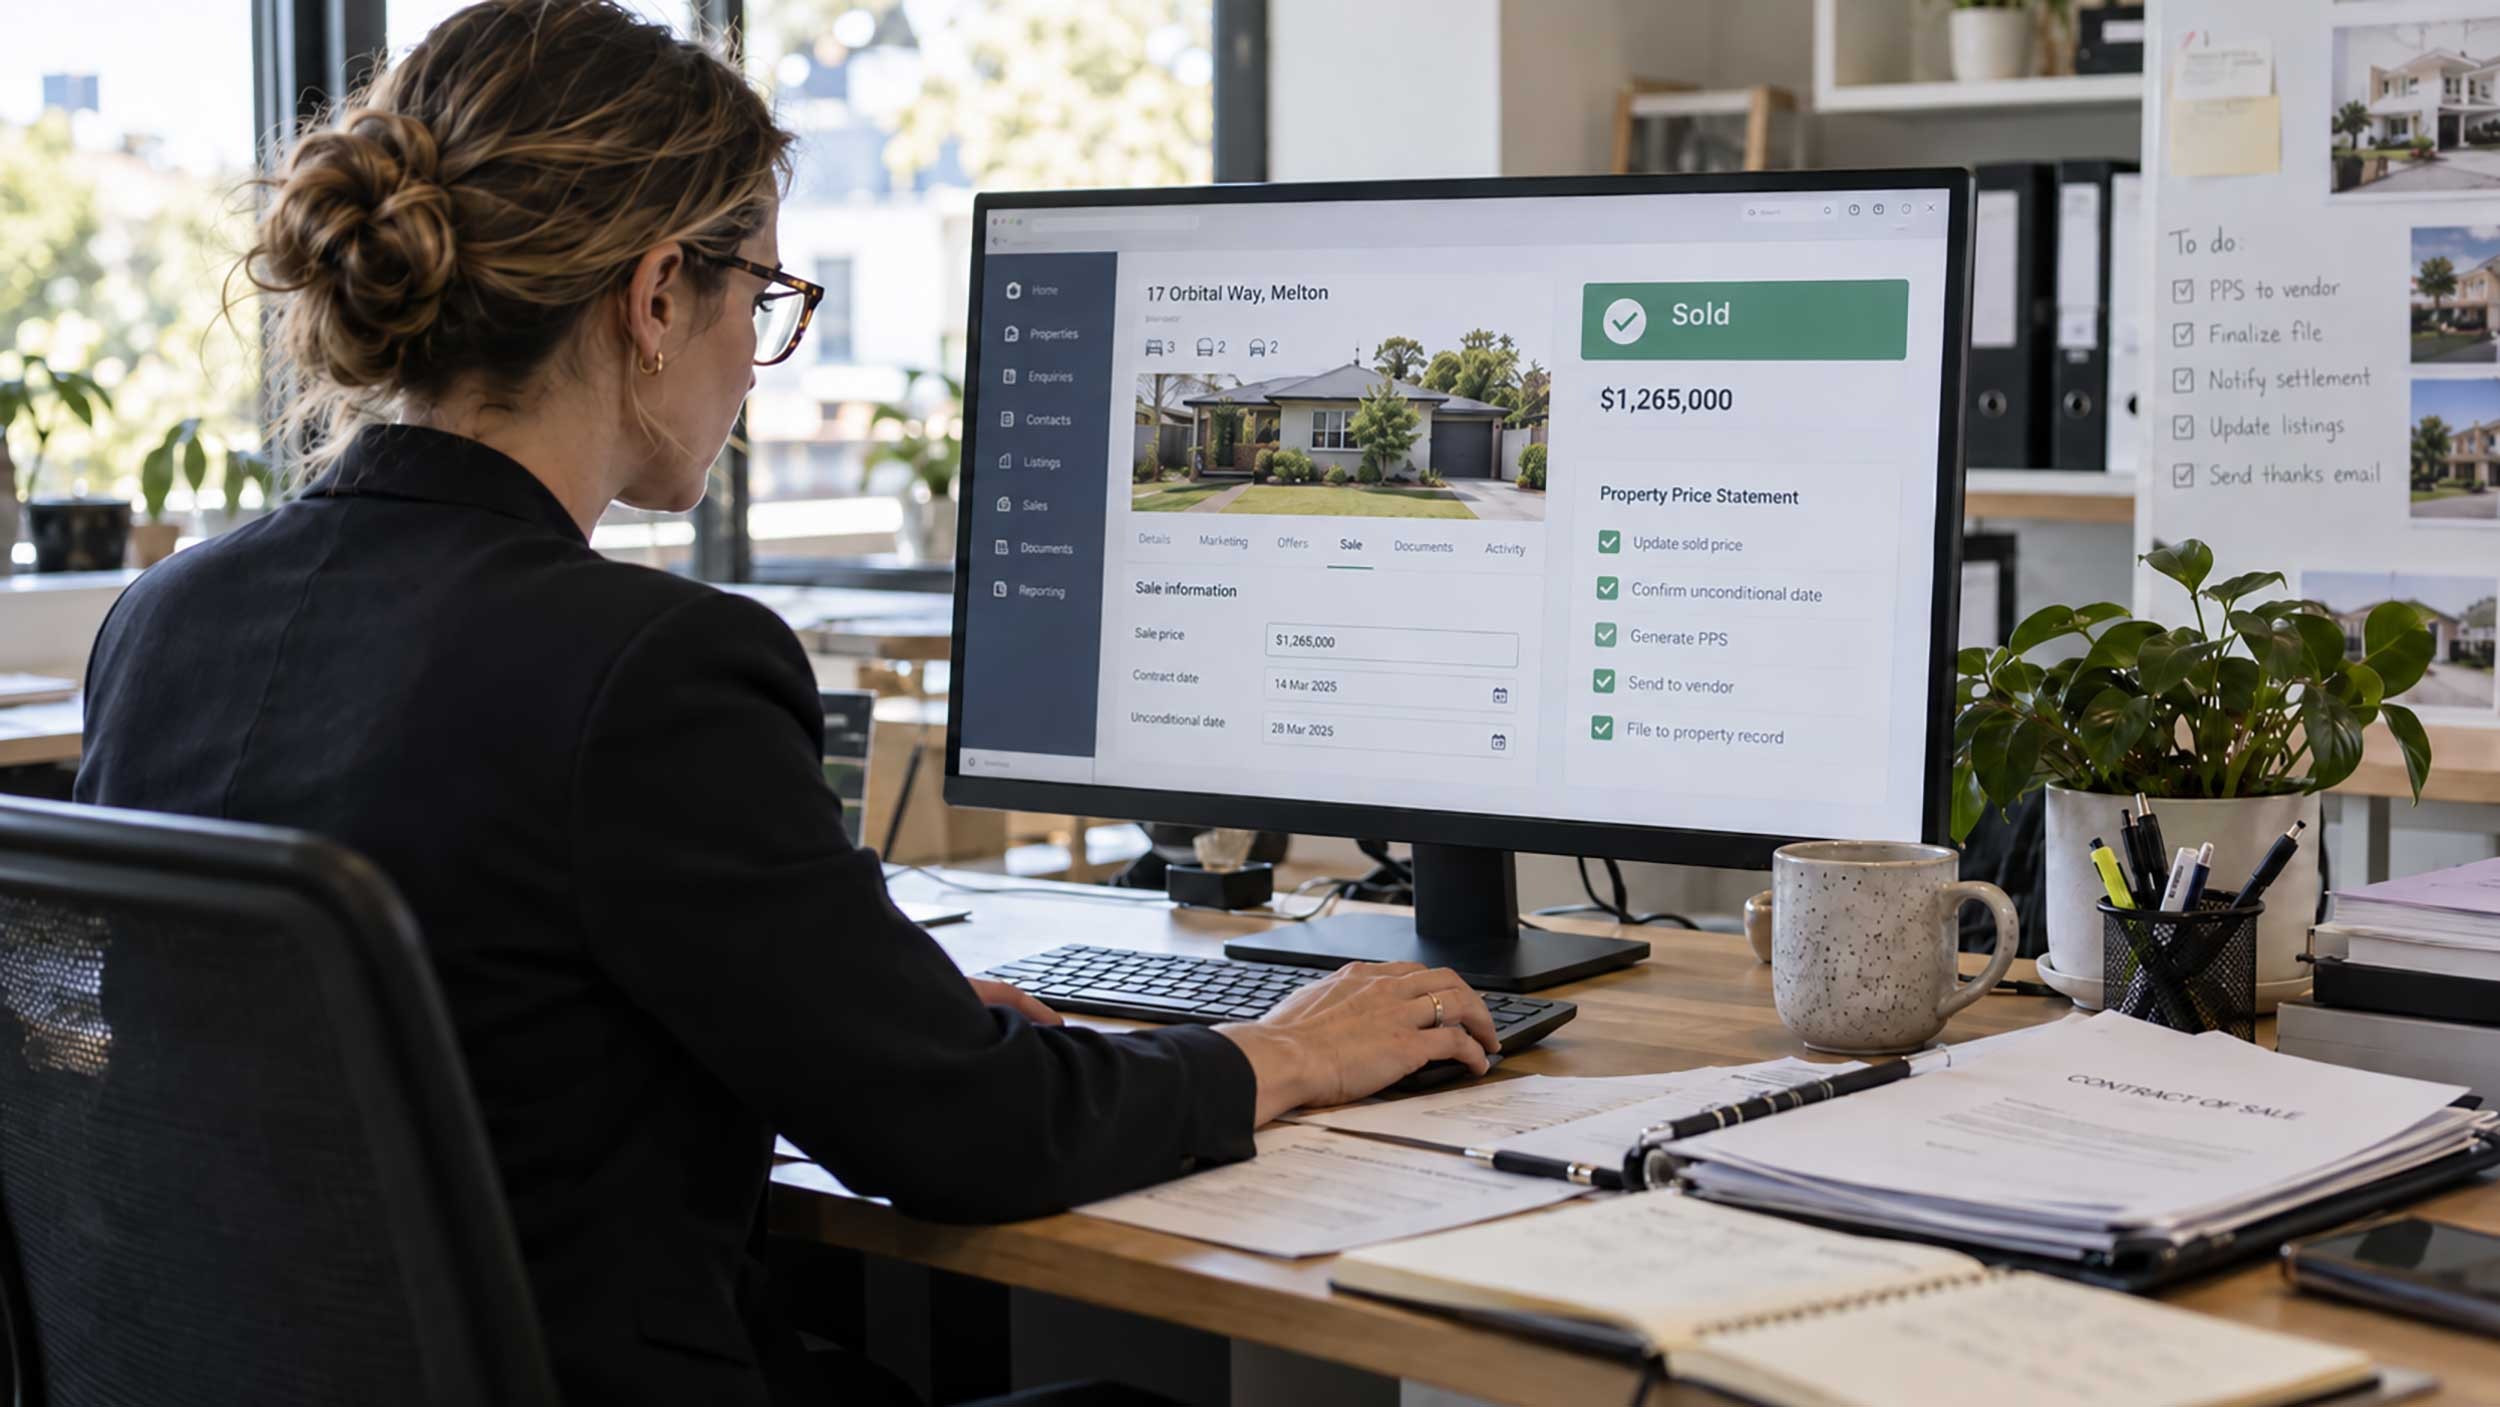
Another major reform is the mandatory publication of applicable final sale prices. For sales becoming unconditional on or after 1 October 2026, agents generally need to update the Property Price Statement with the final sold price within seven days after the contract becomes unconditional.
The updated PPS must then remain publicly available online and free of charge for at least 18 months after the sale becomes unconditional. Both requirements are confirmed in CAV’s sold-price disclosure guidance.
This requirement means agencies need reliable procedures for identifying when a contract becomes unconditional rather than relying only on the settlement date. The obligation can also apply where the property was listed, or the contract was signed, before 1 October 2026 if the sale becomes unconditional on or after that date.
A transitional exception applies in certain circumstances where the agent’s written engagement or appointment to sell was entered into before 1 October 2026 and contains a term requiring the sale price not to be disclosed. Transitional transactions should therefore be checked individually rather than assuming the contract date alone determines whether disclosure is required.
Are there exemptions from publishing the sold price?
There are limited circumstances in which an exemption from publishing the sold price may be available. A seller, purchaser, estate agent or agent’s representative acting on behalf of a seller or purchaser can apply to the Director of Consumer Affairs Victoria where circumstances involving family violence or personal violence affect the seller or purchaser.
A general preference for keeping the sale price private is not sufficient by itself. Importantly, an agent must not publish the sold price while a valid exemption application is under consideration, and the sale price must remain undisclosed if the exemption is approved. Further information is available through CAV’s sold-price exemption guidance.
Recordkeeping under the new Property Price Statement laws
The new obligations make accurate recordkeeping particularly important. Agencies should maintain clear records identifying matters such as the contract sale price, when the sale became unconditional, when the sold price was published, whether an exemption applied and the basis for relying on an exemption.
Records should also support reserve-price recommendations and confirmations, comparable-property selection, advertising changes and other significant pricing decisions. CAV notes that agents can be required to provide information or documents supporting their selection of comparable properties and the reasonableness of their pricing decisions.
Compliance systems become increasingly important as people progress into senior agency roles. Connect Skills Institute’s real estate courses for Melbourne and Victoria provide information about training pathways covering Victorian real estate practice, legislation, marketing, sales and agency responsibilities.
Penalties for breaching Victorian underquoting laws
Agents should treat pricing and disclosure requirements as core statutory responsibilities rather than optional administrative procedures. Consumer Affairs Victoria states that agents who do not comply with underquoting laws can face a penalty of 240 penalty units, while more serious offences can also have consequences for commission received from the sale.
The Victorian Department of Treasury and Finance has set the value of one penalty unit at $209.10 for 1 July 2026 to 30 June 2027. At that rate, 240 penalty units equals $50,184. Because penalty-unit values are indexed, agents should check the current value rather than relying permanently on a dollar figure quoted in an older article or guidance document.
Consumer Affairs Victoria compliance activity
Consumer Affairs Victoria conducts compliance and enforcement activity relating to property pricing and underquoting. Its compliance work can include reviewing sales files, monitoring property campaigns and investigating suspected breaches, with regulatory responses depending on the circumstances.
For agencies, the practical lesson is that documentation should demonstrate not only the final price information published to consumers but also how pricing decisions were reached and when required changes were made. Clear procedures help staff comply consistently and can provide evidence of the steps taken if an agency’s conduct is later reviewed.
Further Victorian property-law changes in 2027
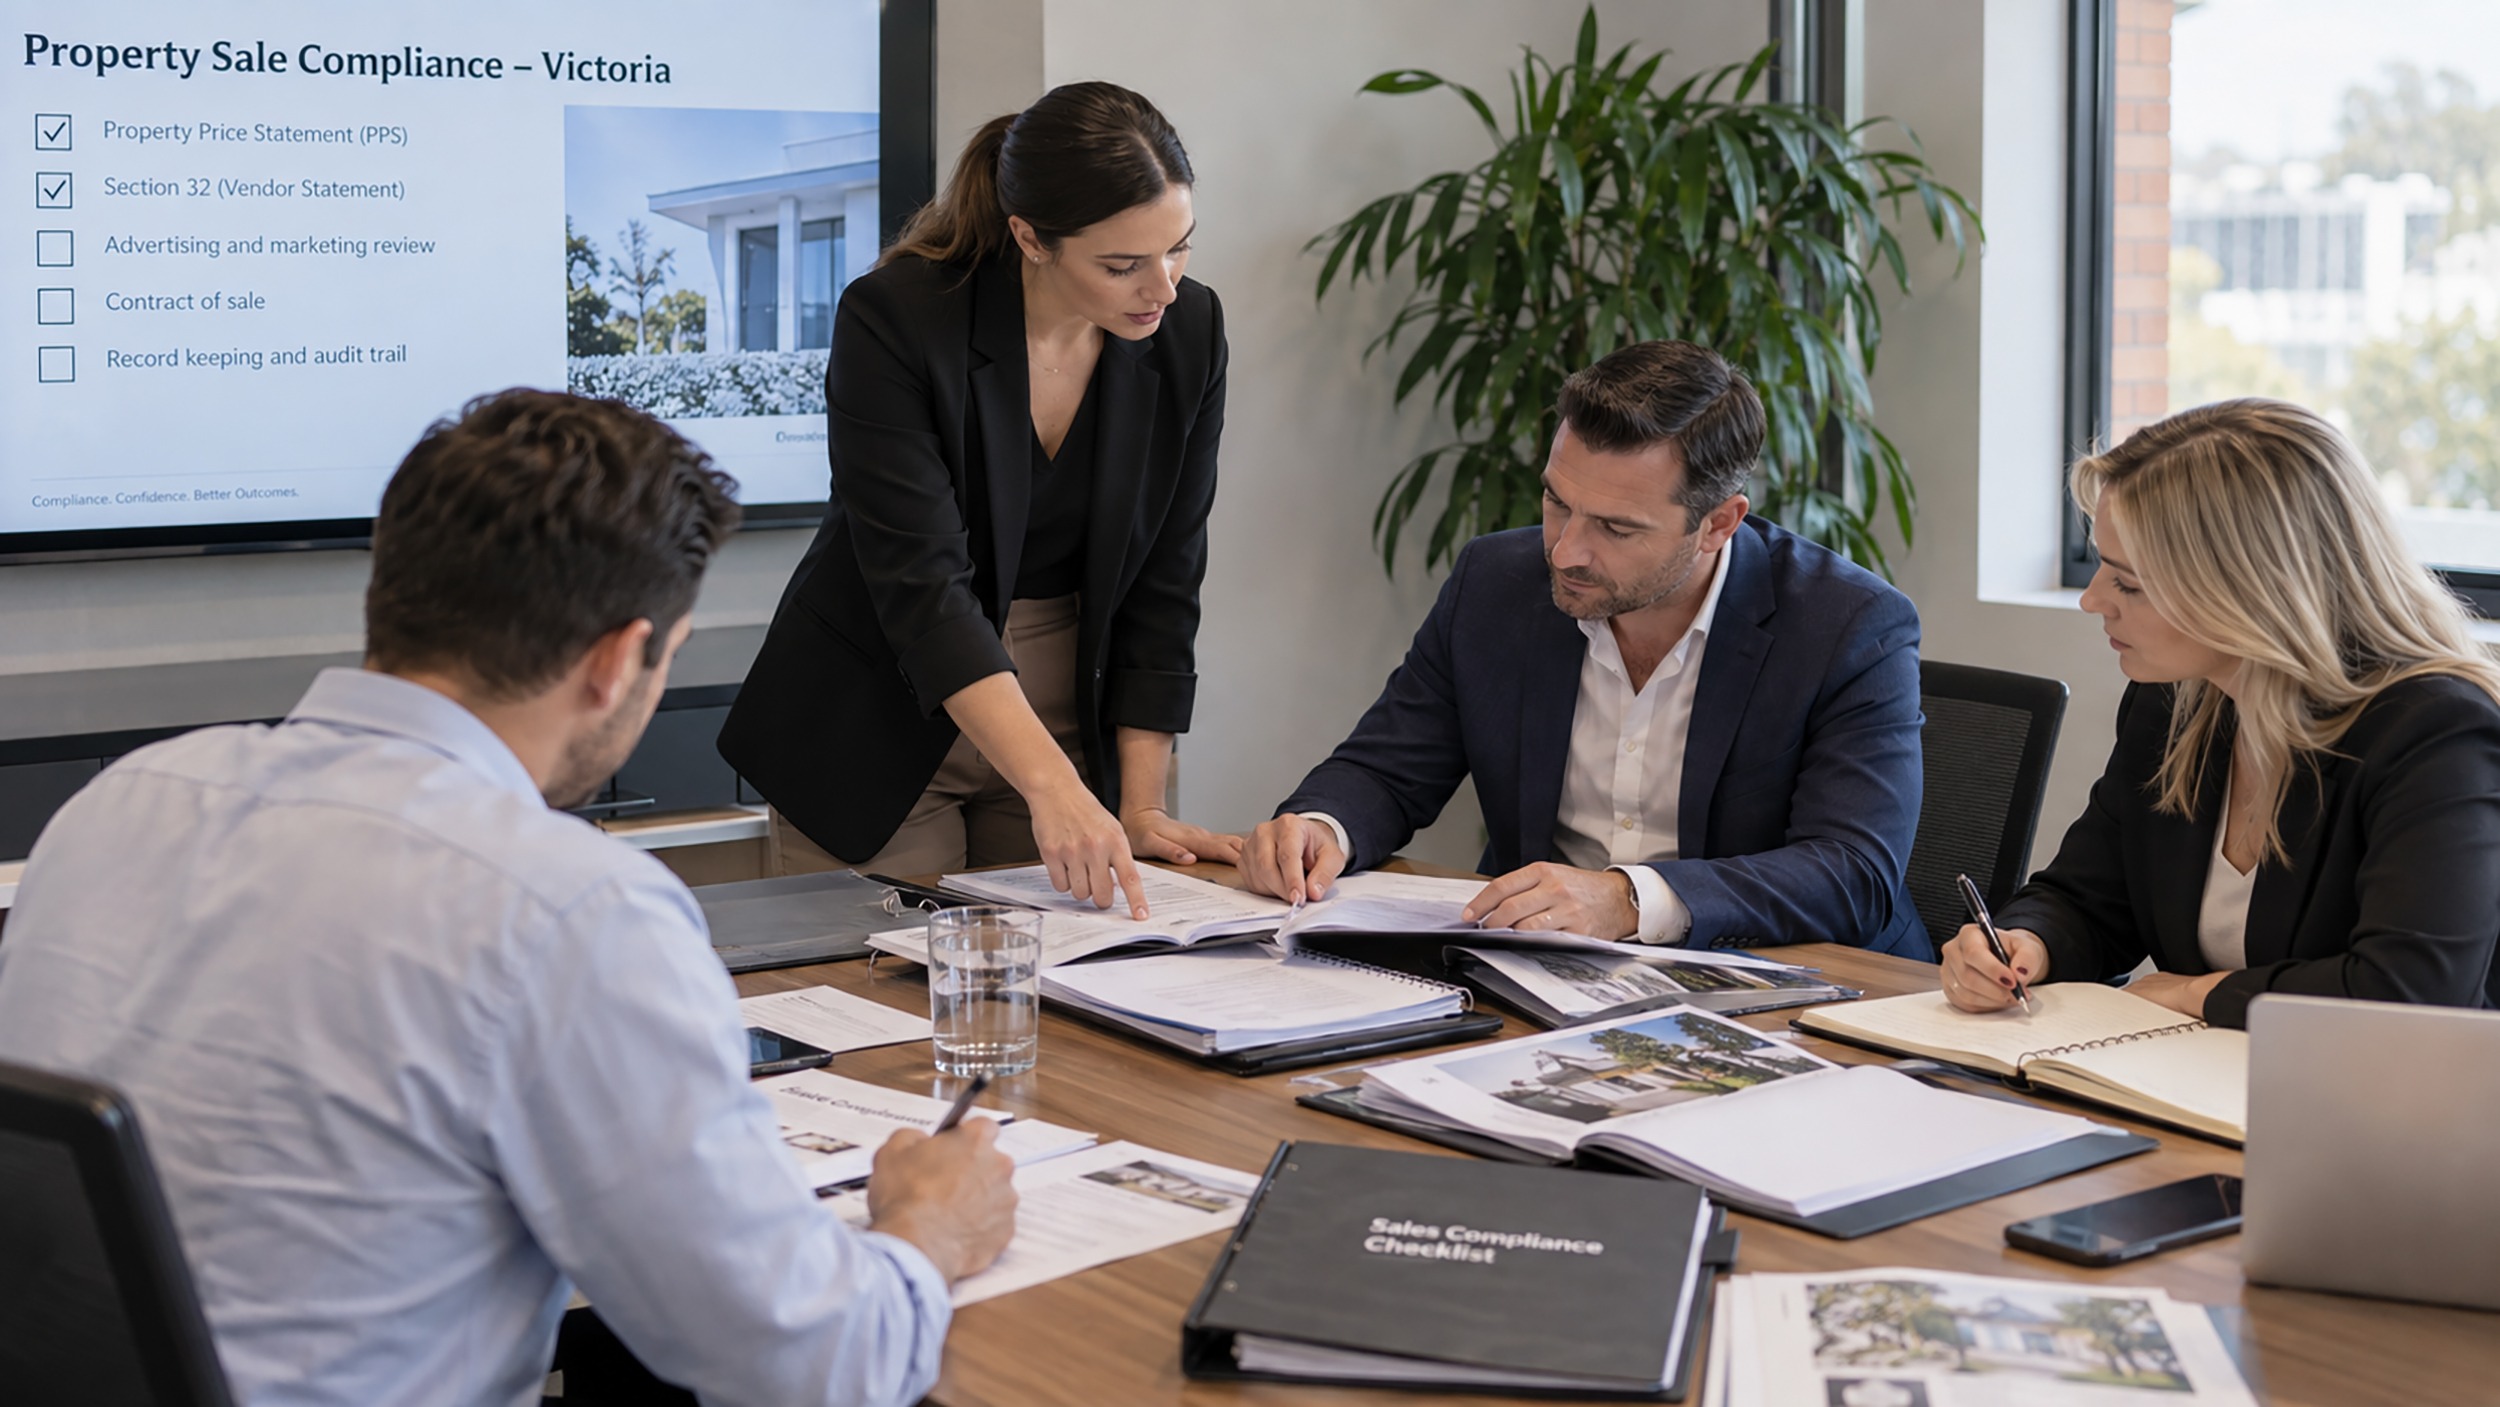
The October 2026 Property Price Statement reforms are not the final changes agencies need to prepare for. Additional reforms commence during 2027, so agencies should continue reviewing procedures rather than treating the October commencement as the end of the implementation process.
Section 32 statements — from 1 June 2027
From 1 June 2027, new timing requirements will apply to Section 32 vendor statements. For private sales, agents must make the statement available within 14 days after the property is advertised, while for auctions and fixed-date sales the statement must generally be available at least 14 days before the scheduled sale.
Where a property is not advertised, or where it will be sold within 14 days of being advertised, the statement must be available before the purchaser signs the contract. The commencement date and requirements are included in CAV’s 2027 reform timetable.
Early release of deposits — from 1 July 2027
From 1 July 2027, the existing statutory process for early release of a deposit will be repealed. Sellers and purchasers will instead be able to agree to an early release by including an appropriate condition in the contract of sale.
From the same date, agents must not take their commission directly from a deposit released before settlement or rescission of the contract. Sellers can separately choose to pay an agent’s commission before settlement or rescission, which should be distinguished from taking the commission directly from the released deposit.
Sold-price information to Consumer Affairs Victoria — from 1 December 2027
From 1 December 2027, agents will also be required to provide prescribed sold-price information to the Director of Consumer Affairs Victoria unless an exemption applies. This creates another future reporting obligation that agencies should account for when designing post-sale procedures and recordkeeping systems.
What should Victorian real estate agencies review now?
The reforms affect multiple parts of a sales campaign, so agencies may benefit from reviewing the entire workflow rather than treating the PPS as a form to be completed once and filed away. Responsibility for each step should be clear between salespeople, agents’ representatives, administrators, auctioneers and management.
- Use the current approved Property Price Statement forms.
- Review procedures for selecting comparable properties.
- Record the key features and measurements required for the PPS.
- Document reserve-price recommendations and seller instructions.
- Monitor the seven-day reserve-price disclosure deadline.
- Check agency websites and property portals for correct PPS placement.
- Review physical advertising, QR codes and direct PPS links.
- Have procedures for rejected written offers and pricing changes.
- Record when contracts become unconditional.
- Publish applicable sold prices within the required timeframe.
- Keep the completed PPS publicly available for the required period.
- Build exemption procedures into post-sale workflows.
- Prepare for the additional reforms commencing throughout 2027.
A checklist is useful only if people understand why each step exists and who is responsible for completing it. Agencies should combine documented procedures with current regulator guidance and appropriate staff training, particularly where different employees manage listing data, advertising, sales negotiations and post-sale administration.
Frequently Asked Questions About Property Price Statement Guidelines
Does the Property Price Statement replace the Statement of Information?
Yes. The Property Price Statement (PPS) has replaced the former Statement of Information. The new requirements commenced from 1 October 2026 for applicable residential sales, with the new PPS requirements applying to auctions and fixed-date sales held on and from 16 October 2026.
Do the new Property Price Statement laws apply to commercial properties?
The Victorian underquoting requirements discussed in this article apply to residential property sales. Consumer Affairs Victoria states that these underquoting laws do not apply to rural, commercial or industrial property sales, although other obligations such as Australian Consumer Law requirements concerning misleading representations can still apply.
What information must be included in a Property Price Statement?
The PPS includes applicable pricing information, comparable-property information and prescribed information about the property being sold. The new requirements also include key characteristics such as building type, bedrooms, bathrooms, car spaces, internal floor area and land area for the subject property and relevant comparable properties.
What happens if an agent can find only one or two comparable properties?
If three qualifying comparable properties cannot be identified but one or two qualifying properties are available, the agent must take those properties into account when determining the estimated selling price. The available comparable properties must then be appropriately identified in the Property Price Statement.
Where must the Property Price Statement appear in an online advertisement?
The PPS must be displayed or linked within the first visible part of the main online property advertisement and immediately next to the advertised property price. This is substantially more prominent than the previous practice of placing a Statement of Information link near the bottom of a listing.
Can an auction proceed if the reserve price has not been published for seven days?
No. Where the new reserve-price disclosure requirements apply, the auction or fixed-date sale cannot proceed unless the seller’s reserve price has been publicly available for the required seven-day period.
What happens if the seller changes the published reserve price?
If a seller changes an already published reserve price, the seven-day disclosure period starts again. The revised reserve generally needs to remain publicly available for another seven days before the auction or fixed-date sale can proceed, whether the change increased or decreased the reserve.
Can a property still be sold before a scheduled auction?
A prospective purchaser can still make a pre-auction offer and the seller can decide whether to accept it. If the property is sold through a private agreement before the auction, the scheduled auction can then be cancelled, although the agent must continue complying with the applicable pricing, disclosure and sales requirements.
When must the final sold price be published?
Unless an exemption applies, the final sale price must be added to the Property Price Statement within seven days after the sale becomes unconditional. The updated PPS must then remain available online, free of charge, for at least 18 months after the unconditional-sale date.
Can a seller or purchaser ask for the sold price to remain private?
A general preference for privacy does not automatically create an exemption. An application can be made where circumstances involving family violence or personal violence affect the seller or purchaser, and the sold price must not be published while an applicable exemption application is being considered.
Where can agents obtain the approved Property Price Statement forms?
Consumer Affairs Victoria publishes the current approved PPS forms for properties within and outside metropolitan Melbourne, including forms for single residential properties and multiple units of a single type or class. Agents should use the current CAV Property Price Statement forms rather than relying on an older Statement of Information template.
Preparing for the New Property Price Statement Laws
The New Property Price Statement Laws represent a substantial change in Victorian residential real estate practice, and the reforms go well beyond renaming the Statement of Information. Agents need to consider the PPS throughout the sales process, from researching comparable properties and preparing advertising through to establishing the reserve price, dealing with written offers, identifying when a contract becomes unconditional and publishing the final sold price.
For people entering the Victorian property industry, the reforms also demonstrate why professional real estate practice requires an understanding of legislation, ethics, advertising, documentation and agency procedures in addition to sales skills. Connect Skills Institute provides information about real estate courses for Melbourne and Victoria for students considering a career in the industry.
People beginning their real estate careers can also review the CPP41419 Certificate IV in Real Estate Practice. The qualification includes areas such as professional practice, ethical practice, legislation, marketing, property appraisal and property sales.
Experienced industry participants considering progression towards an estate agent licence can explore the Estate Agents Licence Course Bundle Victoria, while readers researching the broader licensing pathway may also find our guide on how to become a licensed real estate agent in Melbourne and Victoria useful.
For currently practising agents and agencies, the practical message is straightforward: check current Consumer Affairs Victoria guidance, review internal sales procedures and ensure staff understand which events trigger each disclosure requirement. Clear systems, documented responsibilities and continuing professional awareness can help agencies respond consistently as the 2026 reforms operate in practice and further changes commence during 2027.
